Mortgage advisory · Glendale, California
A mortgage should
fit the life of the
borrower.
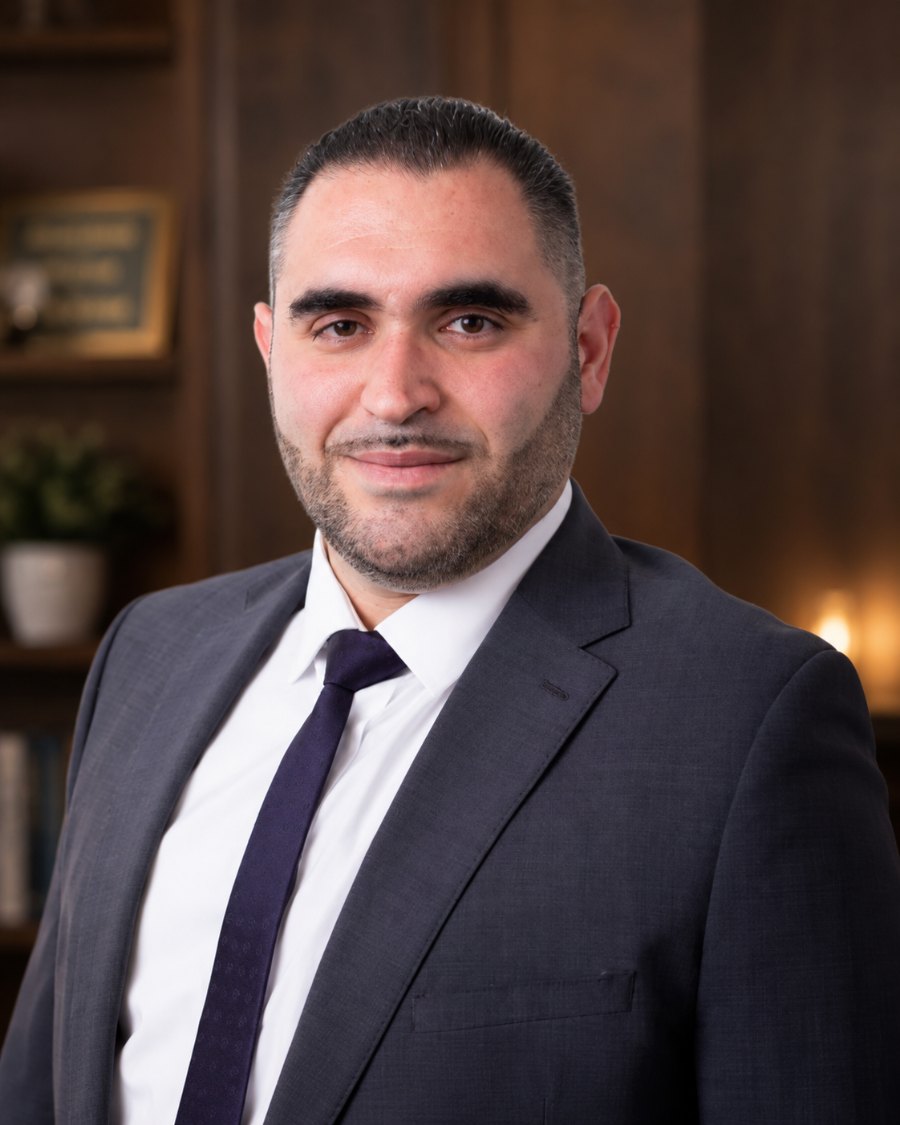
Sevak Markossian is a Glendale-based mortgage loan officer (NMLS #524738) with more than 18 years of experience in banking and residential lending. He helps homebuyers and homeowners navigate purchase, refinance, and jumbo financing throughout Glendale, the San Fernando Valley, the San Gabriel Valley, and communities across California.
- 18+
- Years in finance
- 15+
- Lending partners
- 524738
- NMLS number
- 2
- Languages spoken
- 24 hrs
- Typical pre-approval turnaround*
*After receipt of complete credit, income, and asset documentation. Timing may vary.
About
- NMLS
- 524738
- Tenure
- 18+ years
- Brokerage
- Apex Home Loans
- Languages
- English · Armenian
- Office
- Glendale, CA
A career built on listening first, lending second.
Sevak Markossian began his career inside one of America's largest financial institutions, where he spent more than a decade in leadership, business banking and district roles. He trained senior leaders in customer experience management and learned that the best financial outcomes start with understanding what a family is actually trying to achieve.
He brought that orientation into mortgage lending. Today he guides homebuyers and homeowners through the single largest transaction most people ever undertake, on the principle that clear communication is non-negotiable from the first conversation to the final signature.
Working from Apex Home Loans on Brand Boulevard, Sevak serves families across the San Fernando, San Gabriel and Crescenta Valleys, and originates loans for clients throughout California. Whether it is a first condo in Burbank or a hillside estate in La Cañada, the standard of care does not change.
“My role is to give every client real options, full transparency, and a clear path from application to closing.”
Sevak Markossian · NMLS 524738
The right loan is the one that fits.
A loan program is a tool, not a brand preference. Select one to see where it does its best work.
Conventional loans
The workhorse of American home financing, conventional loans are designed to meet Fannie Mae or Freddie Mac guidelines. They offer competitive rates for qualified borrowers with documented income and credit. Fixed- and adjustable-rate options are available, with terms ranging from 10 to 30 years, depending on the program and lender.
- Minimum down
- 3%
- Minimum credit
- 620
- LA County limit
- $1,249,125
- PMI
- Below 20% down
Loan limit shown is for a one-unit property in Los Angeles County for 2026. Rates, terms, and qualification requirements vary by lender and borrower profile.
Strongest fit when
- You have established credit and documented income
- Buying a primary residence, second home, or investment property
- You prefer conventional financing without government-loan requirements
- You want the opportunity to remove mortgage insurance after building sufficient equity
- You prefer predictable payments with a fixed-rate mortgage
FHA loans
Government-insured mortgages designed to expand access to homeownership. FHA loans may allow lower credit scores, smaller down payments, and more flexible qualifying guidelines than conventional financing—making them a practical option for first-time and repeat homebuyers.
- Minimum down
- 3.5%
- Minimum credit
- 580
- LA County limit
- $1,249,125
- Mortgage insurance
- Upfront + annual MIP
A 3.5% down payment generally requires a minimum 580 credit score. Lender requirements may vary. Loan limit shown is for a one-unit property in Los Angeles County for 2026.
Strongest fit when
- Lower credit score or limited down-payment savings
- Purchasing a primary residence with as little as 3.5% down
- Credit has been rebuilt after a financial setback
- Buying an eligible one- to four-unit owner-occupied property
- More flexible qualifying guidelines are needed
VA loans
A home loan benefit earned through service. Eligible veterans, active-duty service members, National Guard and Reserve members, and qualifying surviving spouses may benefit from no required down payment, no monthly mortgage insurance, competitive rates, and limited closing costs.
- Minimum down
- 0%
- Lender credit requirements
- Vary by lender
- Mortgage insurance
- None
- Funding fee
- 1.25–3.3%
Current purchase-loan funding fees range from 1.25% to 3.30%, depending on down payment and whether entitlement has been used before. No down payment is generally required with sufficient entitlement, although lender and property requirements apply. The funding fee varies by loan type, down payment, and prior use and may be waived for eligible borrowers, including certain veterans receiving service-connected disability compensation.
Strongest fit when
- Eligible borrower with a valid Certificate of Eligibility
- Purchasing or refinancing a primary residence
- Little or no down payment is preferred
- Preserving cash reserves is a priority
- Using or reusing available VA entitlement
Jumbo & Super-Jumbo Loans
Financing above the conforming loan limit — in Los Angeles County, anything over $1,249,125. Because so many homes in Glendale, Pasadena and La Cañada exceed that threshold, jumbo financing is everyday work here.
- Minimum down
- 10–20%
- Typical credit
- 700
- Reserves
- Vary by program
- Rate options
- Fixed, ARM or interest-only
Loan limits shown apply to one-unit properties in Los Angeles County for 2026. Program availability and qualification requirements vary by lender.
Strongest fit when
- Financing exceeds the applicable conforming loan limit
- Strong credit, documented income, and sufficient reserves
- Purchasing a primary residence, second home, or investment property
- Interest-only, fixed-rate, or adjustable-rate options are preferred
- A customized solution is needed for a larger loan amount
Refinance
Replace your current mortgage with financing better aligned with your goals. A rate-and-term refinance may help reduce your interest rate, adjust your loan term, or change loan programs. A cash-out refinance allows qualified homeowners to access available equity for renovations, debt consolidation, investments, or other financial needs.
- Loan options
- Rate-and-term or cash-out
- Available terms
- 10, 15, 20 or 30 years
- Rate options
- Fixed or adjustable
- Closing timeline
- Typically 21–30 days
Refinancing may increase the total finance charges paid over the life of the loan. Qualification, available equity, rates, costs, and terms vary by borrower and loan program.
Strongest fit when
- A lower rate or payment may provide meaningful savings
- You want to shorten or extend your mortgage term
- Removing mortgage insurance could reduce your payment
- You want to change from an adjustable to a fixed rate
- You need to access equity through a cash-out refinance
HELOC & HELOAN
Access your home’s available equity without replacing your existing first mortgage. A HELOC provides a revolving credit line that allows qualified homeowners to borrow as needed, while a HELOAN provides the funds as a lump sum with predictable monthly payments. Both can be used for home improvements, debt consolidation, major expenses, or other financial goals.
- Funding options
- Credit line or lump sum
- Rate options
- Variable or fixed
- Lien position
- Typically a second mortgage
- Loan amounts
- Vary by program
Rates, payments, draw periods, repayment terms, available equity, and qualification requirements vary by lender and program. A HELOC typically has a variable rate, while a HELOAN commonly has a fixed rate and payment.
Strongest fit when
- Your current first-mortgage rate is worth preserving
- You want to access equity without refinancing your first mortgage
- You need flexible access to funds over time through a HELOC
- You prefer a lump sum and predictable payments through a HELOAN
- You are financing renovations, consolidating debt, or covering a major expense
Non-QM & Bank Statement Loans
Flexible financing for borrowers whose income, assets, or property type may not fit traditional lending guidelines. Non-QM options may include bank statement, 1099-only, profit-and-loss, asset-depletion, DSCR, and foreign-national programs—providing alternative ways to document income and qualify.
- Documentation options
- Bank statements, 1099, P&L or Assets
- Typical down payment
- 10%–25%+
- Typical credit
- 660+
- Program options
- Self-employed, DSCR and Asset Depletion
Programs, documentation, credit requirements, down payments, rates, and terms vary by lender and borrower profile. Non-QM loans are not qualified mortgages and may carry higher rates or costs than conventional financing.
Strongest fit when
- Self-employed with significant business deductions
- Income is better documented through bank statements, 1099s, or a profit-and-loss statement
- Investment property qualifies using rental income or DSCR
- Substantial assets are available but reportable income is limited
- A foreign national is purchasing eligible U.S. property
The process
A predictable path from first call to keys.
The mortgage process should feel like a series of small, deliberate steps rather than a wall of paperwork. Here is exactly what happens, in order.
Discovery call
Twenty to thirty minutes on what you want to do, where you stand financially and the timeline you are working with. No application yet.
Pre-approval
A formal review of credit, income and assets. You receive a written pre-approval letter supported by a detailed review of your qualifications.
Shop with confidence
You write offers backed by a real lender call. I stay in close contact with your agent throughout the search.
Underwriting
Once in contract the file moves through processing and underwriting. I stay closely involved throughout processing and underwriting to help address conditions efficiently.
Close and keys
Final disclosures, signing, funding, recording. Most purchase loans close in 21 to 30 days from acceptance.
Calculator
Run the numbers, privately.
A starting point for budgeting, not a quote. Nothing here is recorded or sent anywhere.
Estimated monthly payment
$6,364
Principal, interest, estimated taxes, insurance and PMI where applicable.
- Principal & interest
- $5,056
- Property taxes
- $1,042
- Homeowners insurance
- $125
- Mortgage insurance (PMI)
- Not required
- Loan amount
- $800,000
Where I work
Deeply local. Nationwide reach.
Based in Glendale and serving clients throughout Southern California, with financing options available nationwide through our network of lending partners.
Glendale
Los Angeles County
Typical loan $500K–$3M
Burbank
Los Angeles County
Typical loan $500K–$2.5M
Pasadena
Los Angeles County
Typical loan $600K–$4M
La Cañada
Los Angeles County
Typical loan $1M–$5M+
La Crescenta
Los Angeles County
Typical loan $700K–$2M
Eagle Rock
Los Angeles County
Typical loan $700K–$2M
San Marino
Los Angeles County
Typical loan $1M–$4M
Nationwide reach
Through our lending network
Residential financing options*
Financing availability is subject to state licensing, lender coverage, program eligibility, and borrower qualification.
“Sevak treated our first home purchase like it was the most important transaction of his year. Every question got a real answer, the same day.”
“Refinanced our home of twelve years and the savings paid for our daughter’s first year of college. He ran the math three times.”
“Self-employed for fifteen years and three lenders said no before I called Sevak. He found the right program in a day.”
Questions
Straight answers, before you call.
The questions clients ask most often, answered the way I would answer them on the phone.
Who is Sevak Markossian?
Sevak Markossian is a mortgage loan officer based in Glendale, California, with more than 18 years in banking and residential lending. He holds NMLS #524738 and originates conventional, FHA, VA, jumbo, refinance, HELOC and non-QM home loans through Apex Home Loans, serving Los Angeles County and clients across California.
What is your NMLS number?
NMLS #524738, originating through Apex Home Loans, NMLS #380990. The license record can be verified any time on the NMLS Consumer Access website.
What areas do you serve?
Glendale, Burbank, Pasadena, La Cañada Flintridge, La Crescenta, Eagle Rock, San Marino and the wider San Fernando, San Gabriel and Crescenta Valleys — with financing available throughout California and nationwide through our lending network.
Which loan programs do you offer?
Conventional, FHA, VA, jumbo and super-jumbo, rate-and-term and cash-out refinance, HELOC and HELOAN home equity financing, and non-QM programs including bank statement, 1099-only, profit-and-loss, asset-depletion, DSCR and foreign-national loans.
What is the 2026 conforming loan limit in Los Angeles County?
For 2026 the conforming limit on a one-unit property in Los Angeles County is $1,249,125. Financing above that amount is a jumbo loan, with its own credit, down payment and reserve requirements that vary by lender.
How fast can I get pre-approved?
A full pre-approval is typically issued within 24 hours of receiving credit, income and asset documents. Most purchase loans then close in 21 to 30 days from offer acceptance, depending on appraisal timing and lender conditions.
Do you speak Armenian?
Yes — English and Armenian, with Spanish-speaking assistance available. For many first-time buyer families in Glendale and Burbank, being able to walk through disclosures in their own language changes the whole experience.
How do I reach you?
Call or text (626) 660-7094, email sevak@apexhl.com, or stop by 600 N. Brand Blvd., Suite 230, Glendale, CA 91203. Hours are Monday to Friday 9–6 and Saturday 10–2.
Let's talk about what you are trying to do.
No application, no obligation. A short conversation is usually enough to tell you whether the numbers work.
- Phone
- (626) 660-7094
- sevak@apexhl.com
- Office
- 600 N. Brand Blvd., Suite 230, Glendale
- Hours
- Mon–Fri 9–6 · Sat 10–2